Showing posts with label Tax. Show all posts

Friday, 28 November 2025

FOUND GOLD IN AMMA'S LOCKER? HERE'S THE TAX TRUTH!


Many families discover gold jewellery in a parent’s locker after their passing — and The first doubt is always the same:

“Will this create income-tax problems if I sell it?”


Here is the clear, factual answer.


🔹 Q1: My mother never filed an ITR. If I sell her gold, will I face trouble?

Short answer: Generally, NO.

Indian mothers accumulate jewellery over an entire lifetime:

via wedding gifts, festival gifts, small purchases, family traditions.— the Income Tax Department usually accepts it without questioning.

🔸 Remember:

Inheritance is NOT taxable in India.

You can receive gold, money, or property from your parents 100% tax-free.


🔹 Q2: When does tax actually apply?

You pay tax only when you SELL the inherited gold.

Keeping the jewellery → No tax.

Selling it → Capital Gains Tax on profit.


🔹 Q3: How is Capital Gains calculated on inherited gold?

If your mother + you together held the jewellery for more than 2 years then it become LONG TERM ASSET.

Meaning:

Tax = 12.5% on the profit

Profit = Sale Price – Your Mother’s Cost

If the jewellery is old (before 1 April 2001), you can use:

✔ Market value as on 1 April 2001

as the cost.

(This usually helps reduce tax.)


🔹 Q4: Will the tax officer question me since my mother never filed returns?

They may ask, but only if:

The gold quantity is very large,

Family background doesn’t match the amount,

No reasonable explanation exists.

In regular, middle-class and upper-middle-class cases, there is no issue at all.


🔹 Q5: When can it become a problem?

Only in extreme cases where:

⚠ You cannot explain the source of the gold

⚠ The quantity/value is far beyond the family’s known means.

Then the Income Tax department may treat it as unexplained income.

This can attract 60% tax + surcharge + penalty

But this happens only in extreme cases, not ordinary inherited jewellery.


🔹 Q6: What should families do BEFORE selling inherited gold?

✔ Keep old bills, if available

✔ Keep proof of gifting (wedding album, old photos, family records)

✔ Clarify in your ITR that the sale is of inherited jewellery

✔ Pay the rightful Taxes honestly.

These simple steps ensure complete peace of mind.


FINAL WORD :

Receiving inherited gold is tax-free.

Selling inherited gold is taxable only on the profit.

If the jewellery looks like something your mother could have collected over her lifetime…

You are absolutely safe.

Most families worry unnecessarily — the rules are actually simple when explained correctly.


DISCLAIMER :

This is general educational information, not personalised tax advice. Please consult your CA for case-specific guidance.


Regards,

Srikanth Matrubai

AMFI Registered Mutual Fund Distributor ARN-51423

QPFP

NISM Certified Retirement Advisor


All the best,
Regards,
Srikanth Matrubai
MUTUAL FUND DISTRIBUTOR
REBALANCE VOLATILITY CERTIFIED COACH
Srikanth Matrubai, Author of the Amazon Best Seller DON'T RETIRE RICH


You are strongly encouraged to consult your financial planner before making any decision regarding this investment. The views expressed here are the author's personal views and should not be interpreted as a recommendation to invest/avoid.

 
Srikanth Matrubai Author of the Amazon Best Seller DON'T RETIRE RICH

Do read the book and give your valuable feedback and request you to post positive comments on Amazon. https://amzn.to/3cHUM6M/ 

You can purchase the book on Amazon and Flipkart 

For the best of ideas on where to invest to create Mountains of Wealth 
join my TELEGRAM channel
WEALTH ARCHITECT
    https://t.me/joinchat/AAAAAELl4KUnaJzi-JJlDg/

Monday, 31 July 2023

Not posting TAX returns before 31st July ?? THEN...GOD BLESS YOU !!!

If you have ever had such a thought, dismiss it immediately. The disadvantages are significantly huge and the advantages, if any .... ABSOLUTELY ZERO !!!

Filing returns is mandatory for individuals and Hindu Undivided Families (HUFs) with earnings exceeding Rs. 2,50,000.
Once it crosses Rs.2.5 lakhs...then you are supposed to file ITR even if you do not have taxable income (after deductions)
YOU ARE STRONGLY SUGGESTED TO CONTACT YOUR CHARTERED ACCOUNT FOR MORE DETAILS 

If your income does not exceed the tax limit...you have nothing to fear...RELAX
But, if it does cross the Limit...then you better file the returns or you better be prepared to face the Music
 
WHAT IF I AM NOT ABLE TO FILE THE RETURNS?

Not filing an Income Tax Return before 31st July will be held as TAX EVASION and you could get a notice from the Income Tax Department

PENALTY : 


if you cannot pay by then...then thankfully, under Section 234f, you can file by paying a LATE FEE of Rs.1000 before 31st December, if your income is below Rs.5 lakhs
If the income is above 5 lakhs (even 5 lakhs Rs.1) then you will have to pay a penalty of Rs.5000. You will also be liable to pay penal interest (Section 234A) at 1% per month!
Besides the above,  
IF YOU FAIL TO FILE BEFORE 31ST JULY, THE BENEFIT OF CARRY FORWARDING OF ANY LOSSES WILL NOT BE ALLOWED

WANT SOME MORE REASONS TO FILE TAXES ON TIME? 

Well... here goes
You may also be levied a Penalty for CONCEALMENT OF INCOME (IT Department will obviously think you have deliberately concealed the income and not filed the returns)


OH MY GOD! ANY OTHER IMPLICATIONS?

Yes. Definitely.

1.               You will not be allowed to carry forward losses you may have incurred in your business or investments. (Normally this is allowed for up to 8 years and can be set off against Profits). This could affect your Financial situation) However, Loss from House Property is still allowed to be carried forward


2.              
You are disallowed to claim a refund of any Excess Taxes you may have paid.
Sometimes due to some error, oversight, or omission, you may have paid Excess Taxes, or a wrongful TDS may have occurred. In normal Tax Filing, you are entitled to claim a refund and get back your rightful amount but this is disallowed in the case of Belated Return Filing!

3.               You may not get Life Insurance Cover.

Normally Life Insurance Companies require you to submit your IT returns while you are taking a Life Insurance Policy and they may well reject your policy in case of non-submission of IT Returns


4.               Even your Credit Card company may reduce your Credit Limit and may even cancel your Card

5.               Your Credit Standing will get hugely affected and you may face problems while applying for loans....personal loans...home loans...whatever!

Easy loan processing: At the time of applying for a loan, banks ask applicants to furnish copies of tax returns for the past 2-3 years. This helps banks understand your financial position and ability to repay the loan. Providing a copy of returns helps in faster approval.

4.               Some countries may even deny you a VISA if you are not able to submit your IT Returns.


FINALLY, in the worst-case scenario (your bad luck) 

 under sec 276cc you may notice for prosecution and get JAILED with a Rigorous Imprisonment of upto 7 years!!!!!!!!!


A
NY OTHER ADVANTAGE OF FILING RETURNS??


YES.

A person should file IT returns irrespective of whether the income is within the exemption limit. Don’t we need to produce IT return statements when we apply for loans? Exemption is a privilege and we shouldn’t use it as an excuse for not filing returns.


LAST MINUTE TIP :

And, despite your best efforts you still could not file your returns....then note there is still time on December 31st, 2023 to file a


BELATED RETURN is permitted

Finally, you are advised to take the advice of a good qualified Chartered Accountant for all Tax Related Matters.

Best of luck,

Srikanth Matrubai


All the best,
Regards,
Srikanth Matrubai
MUTUAL FUND DISTRIBUTOR
REBALANCE VOLATILITY CERTIFIED COACH
Srikanth Matrubai, Author of the Amazon Best Seller DON'T RETIRE RICH


You are strongly encouraged to consult your financial planner before making any decision regarding this investment. The views expressed here are the author's personal views and should not be interpreted as a recommendation to invest/avoid.

 
Srikanth Matrubai Author of the Amazon Best Seller DON'T RETIRE RICH

Do read the book and give your valuable feedback and request you to post positive comments on Amazon. https://amzn.to/3cHUM6M/ 

You can purchase the book on Amazon and Flipkart 

For the best of ideas on where to invest to create Mountains of Wealth 
join my TELEGRAM channel
WEALTH ARCHITECT
    https://t.me/joinchat/AAAAAELl4KUnaJzi-JJlDg/

Saturday, 11 March 2023

TAX HARVESTING - SIMPLE HACK TO SAVE TAX ON MUTUAL FUNDS AND STOCKS


Taxes and Death are the only things that are guaranteed in life.
Both cannot be avoided, and you must face them.

Thankfully, for taxes, there are some ways where you can legally reduce your outgo and one of them is the least known but very useful called TAX HARVESTING.
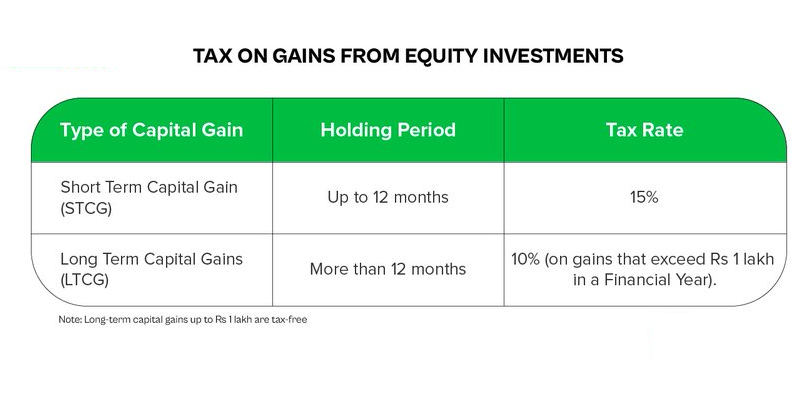
For Capital Gains, there are 2 types of taxes.

Short Term Capital Gains

Long-Term Capital Gains

Short Term Capital Gains are taxed on any profit/gains you made in an asset/instrument within 1 year of purchase (3 years with respect to Debt investment)

Long term Capital Gains are taxed on profit/gains made in an asset/instrument which you are selling AFTER 1 year of purchase


Long Term Capital Gains are taxed at 10% but ONLY when the profit/gains exceed RS.1 lakh

But we are all here for huge profits and not just 1 lakh, isn’t it?
However, you can avoid the Long Term Capital Gains to some extent by using TAX HARVESTING.

HOW DOES TAX HARVESTING WORK?
You sell your Long-Term Capital Gains asset for a profit/gain of Rs. 1 lakh and REINVEST IMMEDIATELY.

Because your Long-term Capital Gains did NOT cross the Rs.1 lakh limit, you DO NOT have to pay any taxes

This, of course, can be repeated year after year.


For example,


suppose you invest Rs.1 lakh in Fund A and it becomes Rs.2 lakhs by year-end….
Sell the same and REINVEST immediately the next day. now your BUYING price (as per Income Tax) becomes Rs.2 lakhs …

Though in reality, your actual cost is still Rs.1 lakh.

Continuing the above example, say in Year 2, your present Rs.2 lakhs become Rs.3 lakhs.. you again sell the same and REINVEST immediately the next day

Your new Buying cost is Rs.3 lakhs!!!

This way, you can ensure you are saving Long Term Capital Gains year after year (to whatever small extent)


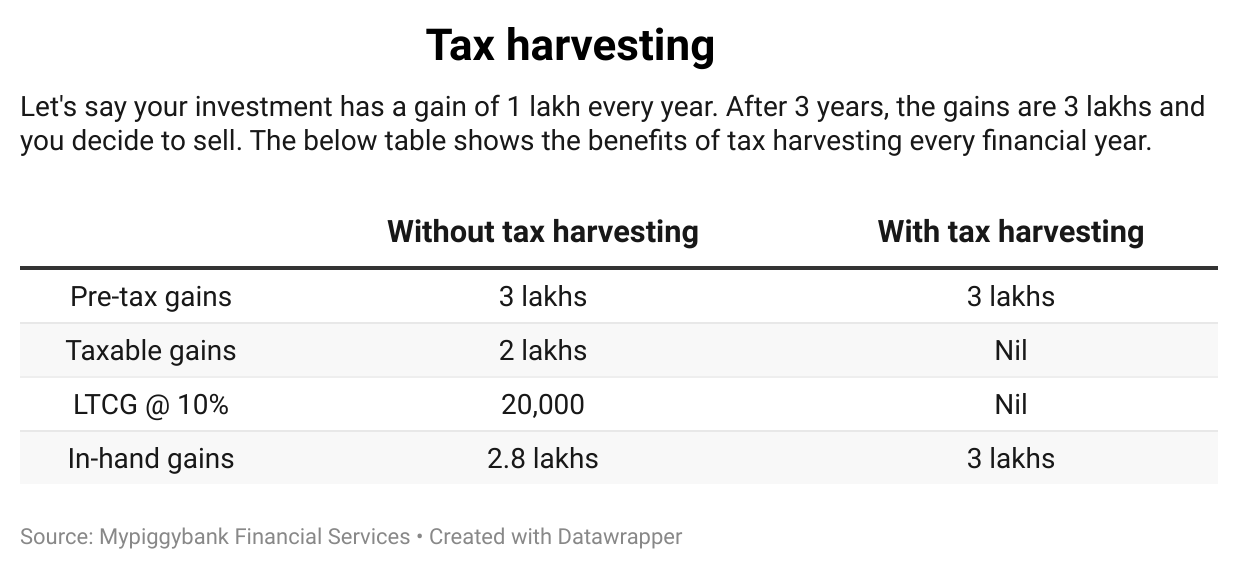
Your Original Buying cost will remain Rs.1 lakh but as per Income Tax, it now becomes Rs.3 lakhs and when you sell for Rs.4 lakh....even though you are sitting on Rs.3 lakhs profits, instead of paying Rs.30,000 tax, you are PAYING ZERO as you have intelligently used the TAX HARVESTING!


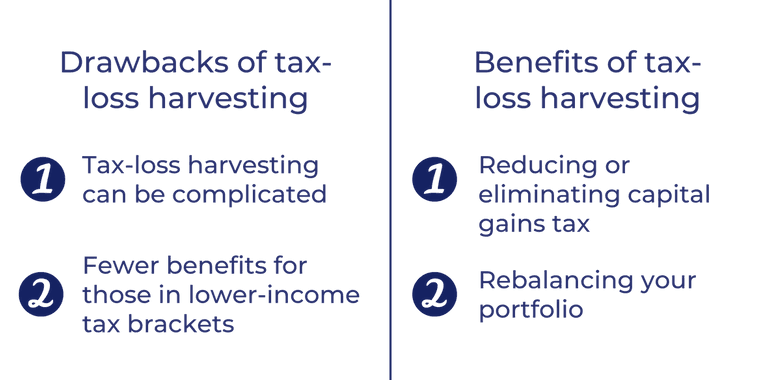
Tax Harvesting is a strategy that helps you minimize tax outgo and potentially help improve your investment returns.


PROS AND CONS

PROS:
1. Of course, you pay LOWER taxes and save the same.

2. Higher returns as you will now have the option of reinvesting the saved taxes

3. Tax harvesting is actually a good tool to RE-BALANCE your portfolio too


CONS:

1. You could end up making your REINVESTMENT price HIGHER due to fluctuations

2. Charges like Brokerage, etc if any

3. Tracking the actual original cost after a few years


ADDITIONAL TIP:
The best option is to invest on the same day so that you don’t miss out on the NAV and for that, you better have some SPACE cash, especially since payouts in equity mutual funds and equities take 2-3 days

One friend of ours… sold his shares to do tax harvesting and planned to buy the same after 3 days but the stock SHOT UP BY 35% IN THAT 3 DAYS !!


NOTE:

Equity Investment is for the LONG TERM and WEALTH CREATION is the goal.  Never lose focus of this whether you do Tax Harvesting or not.

TAX HARVESTING IS TAX PLANNING and not Tax Avoidance or Tax Evasion. So, you can go about it BINDASS!!

Getting “ALPHA” besides the market returns is a challenge and TAX HARVESTING is one of the tools to get that extra ALPHA. 

Its highly recommended to review your investments once a year and the end of the year would be the perfect time as you can also consider whether Tax Harvesting could fit into your strategy for you. 

Strongly suggest and request you to please contact your Chartered Accountant for further details and a way to go about this


All the best,

Srikanth Matrubai


All the best,
Regards,
Srikanth Matrubai
MUTUAL FUND DISTRIBUTOR
REBALANCE VOLATILITY CERTIFIED COACH
Srikanth Matrubai, Author of the Amazon Best Seller DON'T RETIRE RICH


You are strongly encouraged to consult your financial planner before making any decision regarding this investment. The views expressed here are the author's personal views and should not be interpreted as a recommendation to invest/avoid.

 
Srikanth Matrubai Author of the Amazon Best Seller DON'T RETIRE RICH

Do read the book and give your valuable feedback and request you to post positive comments on Amazon. https://amzn.to/3cHUM6M/ 

You can purchase the book on Amazon and Flipkart 

For the best of ideas on where to invest to create Mountains of Wealth 
join my TELEGRAM channel
WEALTH ARCHITECT
    https://t.me/joinchat/AAAAAELl4KUnaJzi-JJlDg/

BOOKS BY AUTHOR

ABOUT

GOODFUNDADVISOR is the musings by Srikanth Matrubai, Author of Amazon Best Selling Book DONT RETIRE RICH. Request you to note that this blog is purely for educational purposes and in no way recommends any investments. Strongly urge you to follow your Advisor We do not take any responsibility whatsoever as the blog content may be changed from time to time and is generic in nature.

Recent Most Popular Posts

THE KING WHO HAD EVERYTHING BUT GOT A GATEKEEPER

In VAMANA AVATAR, Lord Vishnu appeared before King Bali and asked for 3 paces of land. Bali, known for his generosity, agreed ..... unaware ...